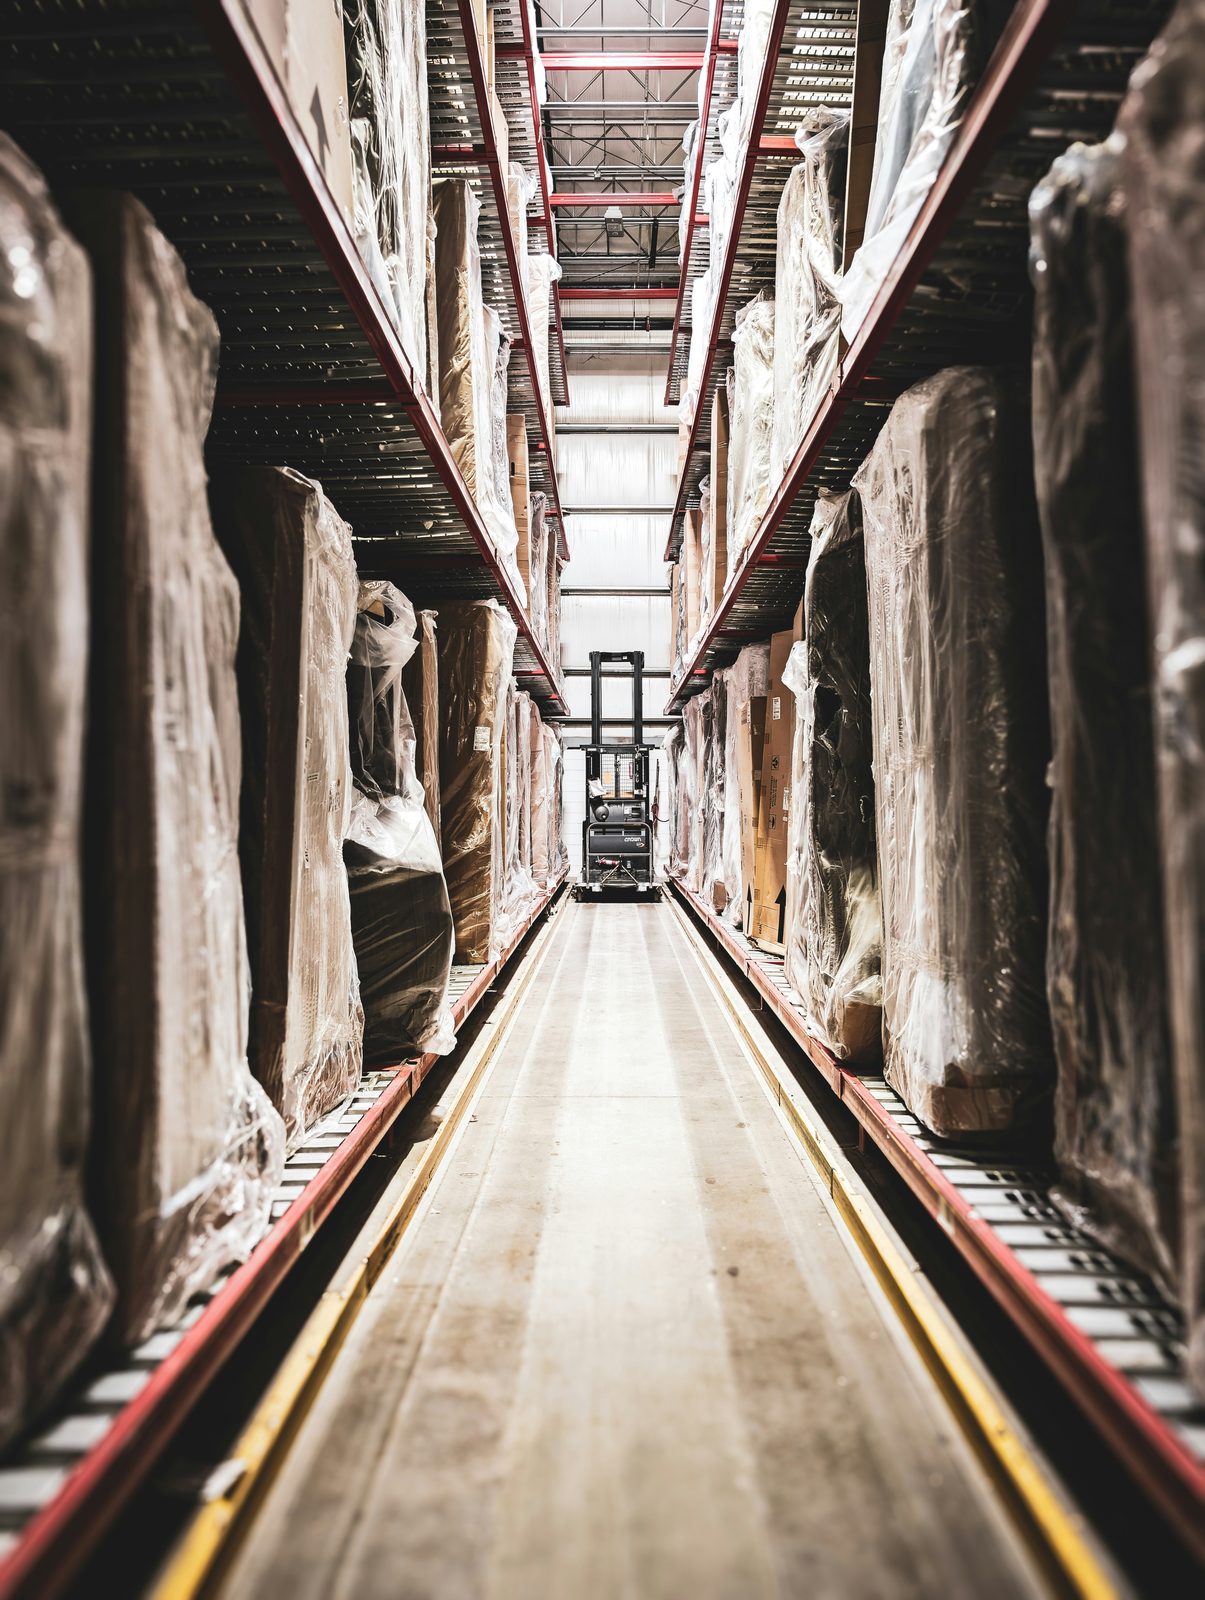
If your business carries physical stock - on shelves, in a warehouse, or at an Amazon FBA facility - that inventory is more than product waiting to sell. It's collateral, and it can be the basis for a revolving line of credit that scales alongside it.
How It's Different From a Term Loan
A term loan gives you a lump sum upfront, which you repay on a fixed schedule regardless of how your sales cycle actually moves. A revolving inventory line of credit works differently: you draw against it as you need capital, repay as inventory sells, and the available credit replenishes. Interest is typically charged only on the amount you've drawn, not the full facility size.
What Determines the Size of the Line
Lenders appraise what your inventory would bring in an orderly sale and extend credit based on that value - typically 50% to 80% of what the inventory cost you. As your inventory grows, so does the amount you can borrow against it.
Who This Tends to Fit
Inventory-based lending is generally a better fit for businesses with real cash-conversion cycles - you buy or manufacture stock, hold it, then sell it - rather than businesses looking for a quick cash advance against future revenue. It tends to suit retailers, e-commerce brands, wholesalers, and manufacturers whose capital needs move with their stock levels rather than a flat monthly number.
If you're trying to figure out whether this structure fits your business, our Lending Products menu has the full breakdown of terms, or you can Contact Us with questions.