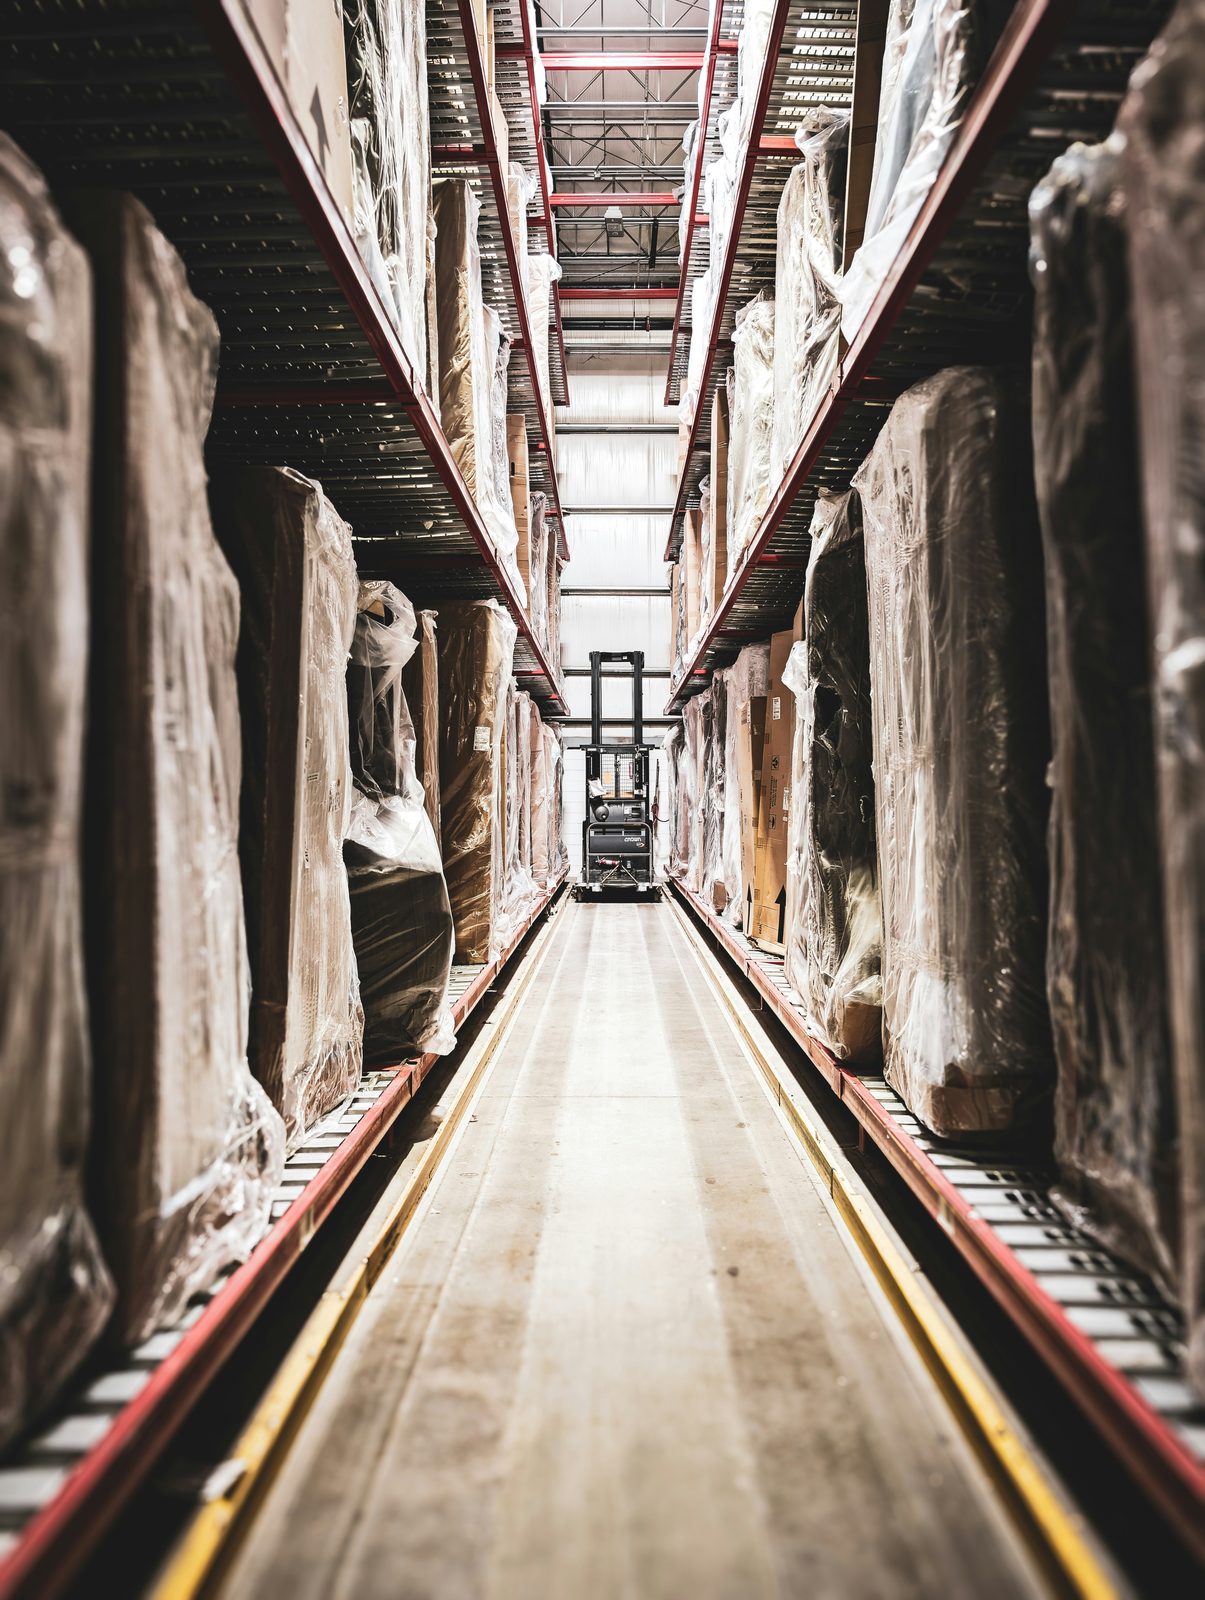
Seasonal businesses face a timing problem that has nothing to do with profitability: the cash goes out to buy or build inventory months before the cash comes back in from selling it. A retailer stocking up for Q4 might be placing purchase orders in June or July, well before a single holiday sale rings up.
The Gap Is Structural, Not a Warning Sign
This mismatch is often mistaken for a red flag by lenders who look only at trailing cash flow. In reality, it's just the nature of an inventory-heavy business. A revolving line of credit tied to the inventory itself - rather than to trailing revenue - is built to absorb exactly this kind of timing gap, because it draws against value that's already sitting on the balance sheet.
What This Looks Like in Practice
- Draw against the line to fund a seasonal purchase order or production run
- Carry the draw through the build-up period
- Repay as inventory sells through and cash comes back in
- Repeat the cycle the next season, without reapplying for new financing each time
Beyond Seasonality
The same structure works for businesses riding a growth curve rather than a calendar - launching a new product line, expanding into a new sales channel, or simply scaling inventory faster than trailing revenue alone would justify to a traditional lender.
If cash flow timing rather than overall creditworthiness is the obstacle, it's worth looking at financing that's structured around the inventory itself. Our FAQs cover common questions on terms and eligibility, or you can Apply Now to start the conversation.